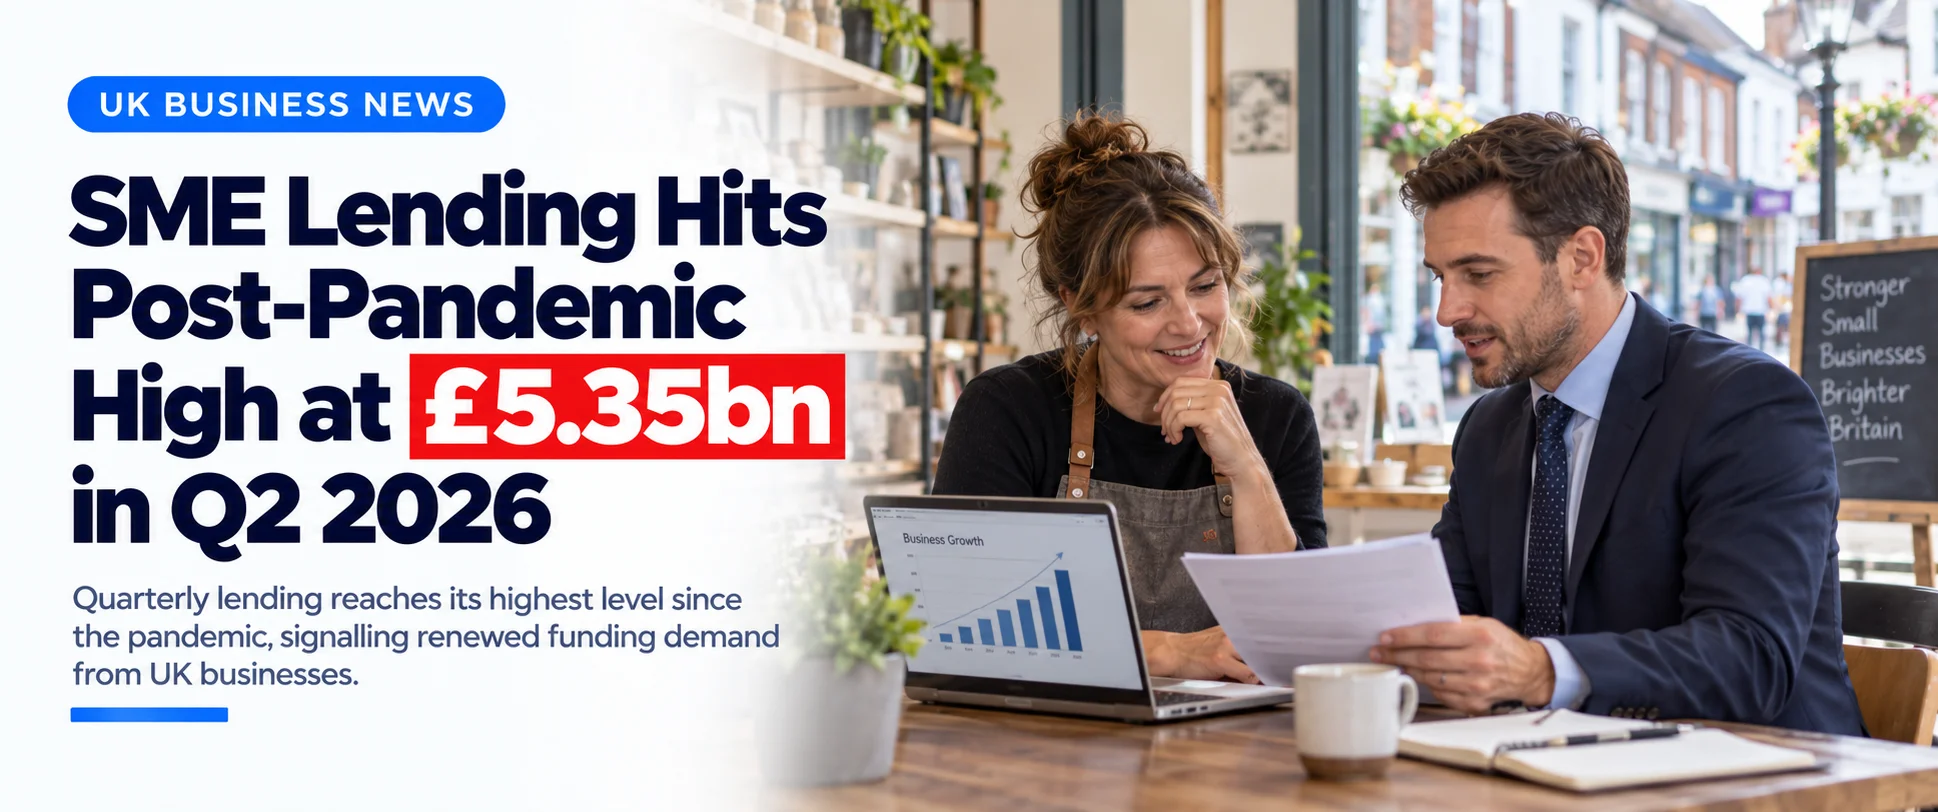
UK small business lending has hit its highest point since the pandemic, but that headline number hides some real pressure building underneath.
New data from UK Finance shows gross lending to small and medium-sized businesses reached £5.35 billion in Q2 2026. That’s up more than 26% compared to the same quarter last year.
On the surface, this looks like good news. Businesses are clearly still getting access to finance. But look closer, and rising overdraft use, uneven demand across sectors, and high borrowing costs tell a more complicated story.
What’s Driving This Growth?
Real estate and professional services stayed among the strongest sectors for borrowing in Q2. Other industries didn’t fare as well. Hospitality and manufacturing saw weaker lending activity, and some businesses leaned more on their existing cash reserves instead of taking on new debt.
Smaller businesses turned more cautious during May and June, largely due to rising energy costs and broader economic uncertainty knocking their confidence.
Medium-sized firms held up better overall, but even they weren’t immune. Loan applications from this group dropped sharply between March and April, falling by 40% according to UK Finance, before picking back up after ceasefire discussions in June.
The takeaway here is simple: business borrowing can shift fast when energy prices, costs, and the wider economy move.
Overdraft Use Hits Its Highest Point Since 2020
Here’s one of the more telling numbers in this data. Businesses used 51.4% of their available overdraft facilities in Q2, the highest level since March 2020.
An overdraft is useful for covering short-term gaps between money coming in and bills going out. But leaning on it too often puts real strain on your working capital.
For SMEs, the real question isn’t just “can I get finance?” It’s “why am I borrowing, and does this type of finance actually fit the need?”
Covering a short-term cash gap calls for a different approach than funding a property purchase or a long-term business investment. Mixing the two up often causes problems down the line.
The Bank of England Held Rates at 3.75%
This lending growth is happening while borrowing costs remain high. On 17 September 2026, the Bank of England voted to hold Bank Rate at 3.75%. Six members of the Monetary Policy Committee backed holding, while three pushed for a rise to 4%. Energy-related inflation is still a major concern behind that decision.
What does this mean for you? Don’t plan your finances around borrowing getting cheaper anytime soon. If your business carries variable-rate debt or relies on your overdraft regularly, keep a close eye on your interest costs and whether you can comfortably keep up with repayments.
What Should SMEs Do Now?
If your business uses finance, review your cash flow before taking on more debt. Start with the basics. How much debt does your business already carry? What does each facility actually cost? When are repayments due? From there, compare your short-term borrowing against your longer-term funding needs, and test whether your cash flow can handle repayments if costs stay high.
Running regular cash-flow forecasts helps you spot pressure before it becomes a real problem. Skip these checks, and you risk rising interest costs, tighter working capital, and less room to absorb any unexpected expenses.
The £5.35 billion lending figure shows finance is still very much available to SMEs. But borrowing should work for your business, not become another source of financial strain.
How Lanop Can Help
Lanop works with UK businesses on cash-flow planning, funding decisions, tax planning, and wider financial strategy, often with the added oversight of a virtual finance director for growing businesses. We look beyond the loan itself, helping you understand how borrowing affects your profitability, tax position, working capital, and future decisions.
If your business is leaning more heavily on overdrafts, or you’re weighing up new finance options, now’s a good time to check whether your current funding setup still makes sense. Contact Lanop today to review your borrowing and cash flow position.