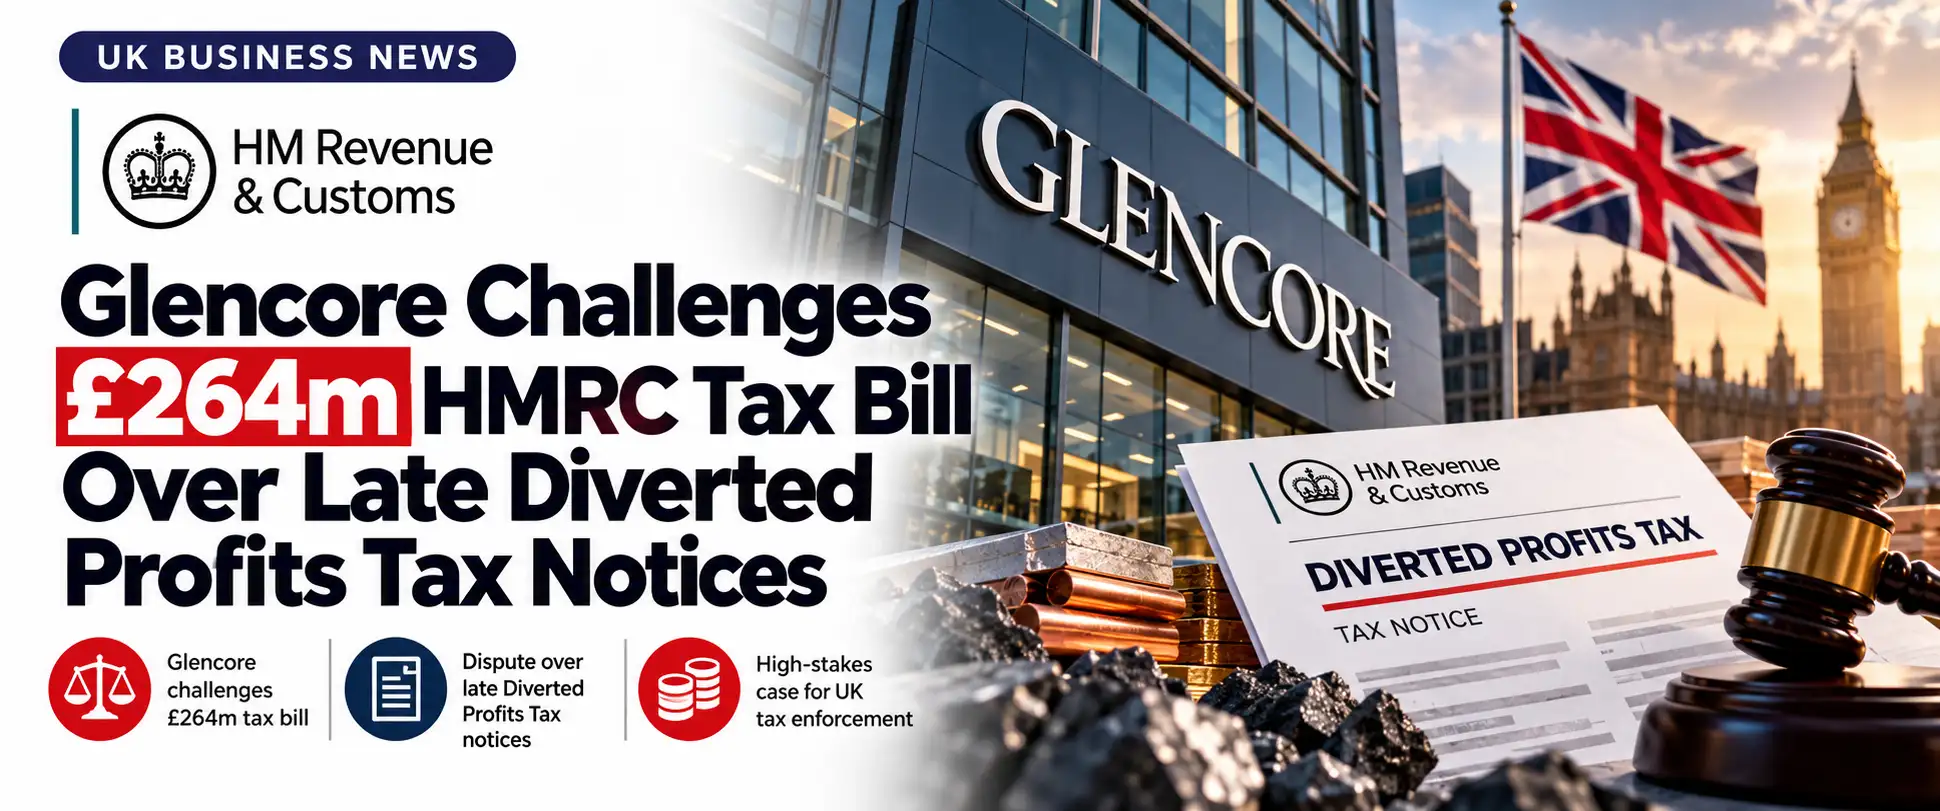
Glencore is challenging a £264 million tax demand from HM Revenue & Customs (HMRC) in the High Court. The dispute centres on whether HMRC issued Diverted Profits Tax notices within the legal time limit.
The case covers two tax periods. HMRC issued demands of about £113 million for 2019 and £151 million for 2020.
Glencore says the notices were issued too late and should not stand. HMRC disagrees and says a longer time limit is applied.
The case is important because it raises a wider question: how closely must HMRC follow the deadlines set by tax law when issuing major tax demands?
Why Glencore Is Challenging the £264m Tax Bill
Glencore’s argument is focused on the timing of the notices. The company says HMRC issued the Diverted Profits Tax notices around 18 months after the normal two-and-a-half-year time limit.
HMRC argues that it had up to four years to issue the notices. Its position is that Glencore had not formally notified HMRC about the relevant cross-border arrangements.
Glencore disputes this. It argues that HMRC was already aware of the arrangements and that the longer time limit should not apply. The High Court must now consider which legal time limit was valid in this case.
How the £264m Dispute Fits into a Wider Tax Battle
The £264 million challenge forms part of a much larger dispute between Glencore and HMRC.
The wider case involves about £1.6 billion in tax assessments linked to accounting periods between 2007 and 2023.
The dispute concerns how profits were allocated between Glencore’s UK operations and its Swiss parent company.
HMRC has challenged these arrangements under transfer pricing and profit allocation rules. Glencore continues to contest the assessments.
Glencore also plans to challenge the wider tax position through arbitration.
Diverted Profits Tax Has Changed Since 2026
The case relates to the old Diverted Profits Tax system because the disputed notices concern 2019 and 2020.
For accounting periods beginning on or after 1 January 2026, Diverted Profits Tax has been replaced by rules covering Unassessed Transfer Pricing Profits within the Corporation Tax system.
This means the Glencore case is historic DPT rules, but the wider issues around transfer pricing and cross-border tax remain relevant.
Why this Matters for UK Businesses
Most UK businesses will never face a tax dispute on Glencore’s scale. However, the case still shows why tax procedure matters. Businesses with overseas parent companies, subsidiaries, management charges, service fees or other related-party transactions need clear records and a sound commercial basis for those arrangements.
It also shows the importance of checking HMRC correspondence carefully. A tax notice should be reviewed not only for the amount claimed, but also for the legal basis, date, and type of notice issued. Ignoring HMRC correspondence can make a tax dispute harder to manage and may reduce the time available to respond.
What Businesses Should Do Now
Companies with cross-border or related-party transactions should review their transfer pricing records and make sure the commercial reasons behind charges are clearly documented.
Businesses should also keep an accurate record of HMRC letters, enquiry dates, and assessment notices.
If HMRC opens an enquiry, early professional advice can help identify the key tax issues before the matter becomes more complex.
How Lanop Can Help
Lanop Business & Tax Advisors supports UK companies with corporation tax, transfer pricing, international tax matters and HMRC enquiries.
Our team can help businesses review cross-border arrangements, maintain clear supporting records, and respond to HMRC in a structured way.
The Glencore case is a reminder that tax disputes are not only about numbers. Procedure, evidence, and timing can matter just as much.