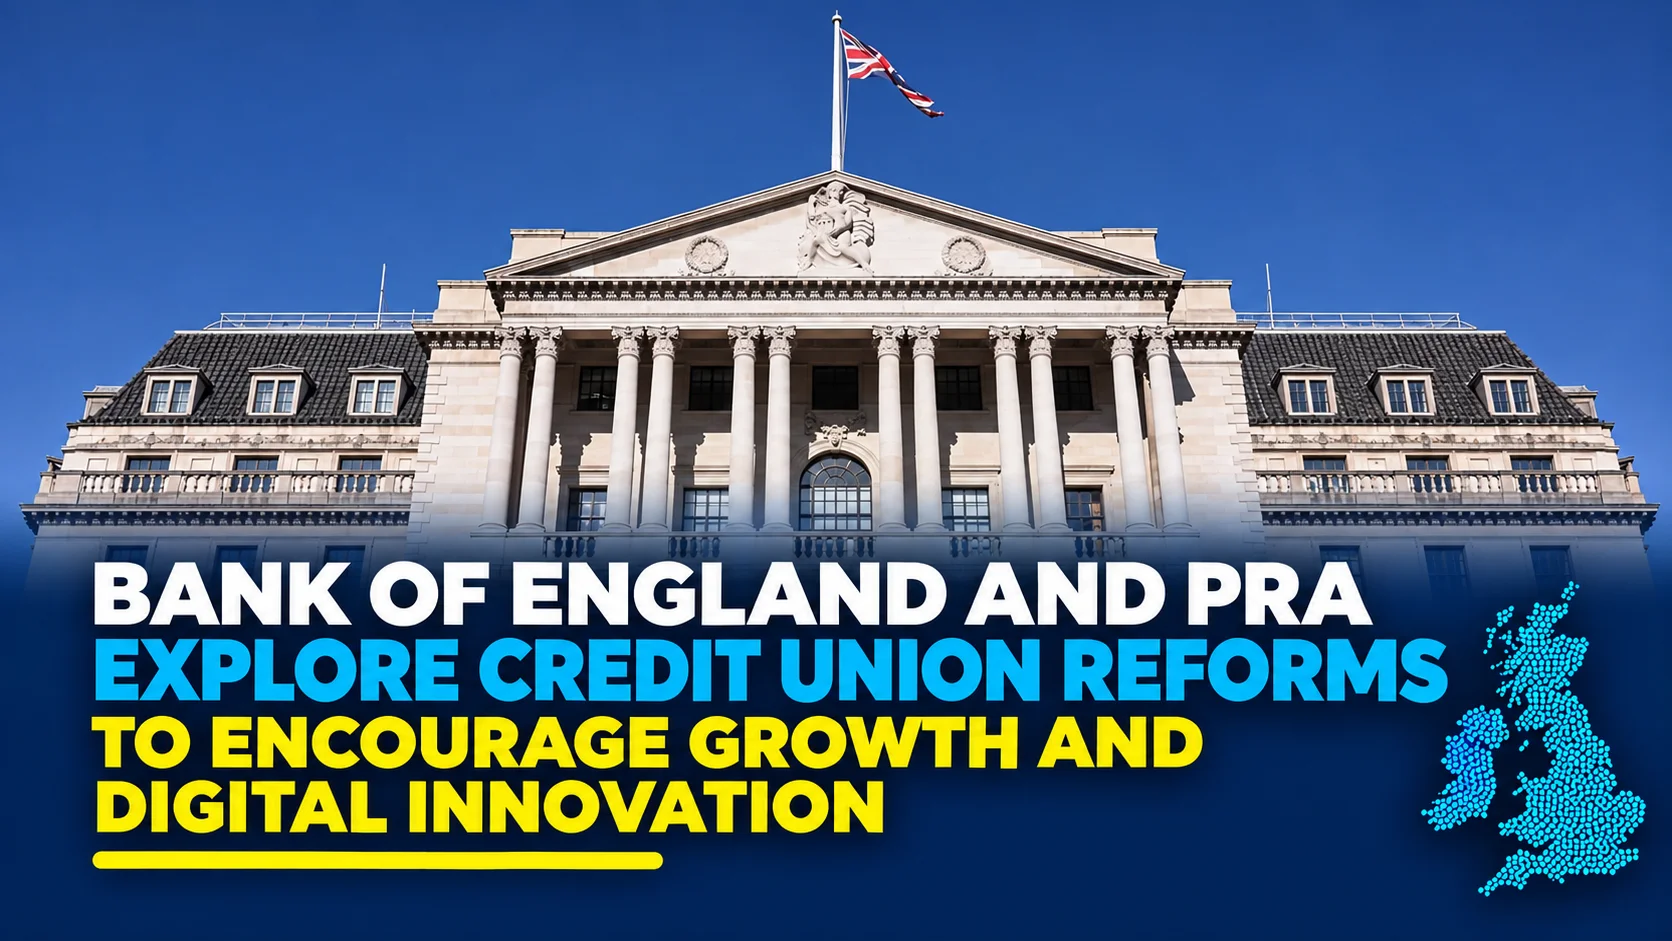
A major review of UK credit union rules began this week. On 3 November 2026, the Bank of England’s Prudential Regulation Authority (PRA) and the Financial Conduct Authority (FCA) issued a joint paper. The aim is simpler rules and safer growth.
The papers, PRA DP2/26 and FCA DP26/1, cover growth, digital tools and costs. No reforms from this review are in force. The review follows the regulators’ 2025 Mutuals Landscape Report.
Why Are UK Credit Union Rules Under Review?
Credit unions are owned by their members. They help people save and borrow. Some serve a town or a group of workers. Others have grown much larger.
The UK has around 340 credit unions. These organizations have over two million members and manage an asset base of £4.9 billion. PRA and FCA are looking for regulations that suit both small and big organizations.
What Changes Could the PRA and FCA Make?
Small credit unions could face less paperwork and simpler checks. The PRA has set out an example for firms with less than £10 million in assets. It could set a 5% capital ratio for that group. This would replace the current 3% minimum for firms with less than £5 million in assets.
For very large firms, the paper looks at tighter checks. One option is a 15% capital ratio for credit unions with assets over £300 million. None is law yet.
The FCA is also looking at whether its fees can be cut. This could free up funds, but no fee cut has been agreed.
How Could Digital Tools Help Credit Unions Grow?
The review looks at how credit unions use outside firms for tech, loans and daily tasks. Shared services may help small groups serve members.
Yet outside help can bring risks. Credit unions must still keep track of data, service faults and how their partners work. The paper does not approve new cloud or instant loan rules.
What About Loan Transfers and Northern Ireland?
The regulators also want views on how credit unions can sell loan books, merge or close in an orderly way. This may include unpaid loans that cannot be recovered after due efforts. Such steps may need a change in law.
A separate PRA paper, CP15/26, looks at rules for credit unions in Northern Ireland. It covers member referrals and ways to share loans. Feedback closes on 12 January 2027. April 2027 is a target, not a set date.
March 2027 Deadline: What Credit Unions Need to Review
Credit unions and firms that support them should assess which options could affect their costs, reserves, reporting, and technology contracts. Feedback on DP2/26 and DP26/1 closes on 5 March 2027. Missing that date means missing the chance to contribute to this stage of the review. Existing rules still apply.
Members, sole traders and small businesses should not assume that new loan products or lower borrowing rates are available. No such change has been announced.
Credit Union Reforms: How LANOP Supports Business Financial Planning
The review may change how firms get funding in the future. But good borrowing choices start with clear money records. LANOP Business & Tax Advisors helps UK business owners check their cash flow. It also helps them look at what a loan will cost. Further, it assists them in planning the effect of repayments on their operations.
Sole traders and small firms often compare a credit union loan with other funding. Good accounts and realistic forecasts help you see the risks before you borrow. LANOP can also help you check how a loan fits your tax plans. We can help with your growth plans while the regulators decide on rule changes.