HM Revenue & Customs (HMRC) has finalised new rules that will make some multinational businesses report their cross-border dealings each year. The regulations were made on 30 October and laid before Parliament on 4 November 2026.
They are due to take effect on 26 November 2026. The new reporting duty covers accounting periods starting on or after 1 January 2027. HMRC estimates that around 75,000 UK businesses may be affected.
HMRC ICTS Rules 2027: What Are the Key Dates?
The new ICTS rules will take effect in stages, giving affected businesses time to prepare for the reporting requirements. The table below highlights the key dates and deadlines multinational businesses need to know.
| Key point | Date or figure |
| Rules made | 30 October 2026 |
| Regulations take effect | 26 November 2026 |
| Reporting starts | Accounting periods from 1 January 2027 |
| Final ICTS notice planned | 26 November 2026 |
| Further HMRC guidance planned | By 31 December 2026 |
| First-year filing concession | No earlier than 30 September 2028 for qualifying periods |
What Must Businesses Report Under the New ICTS?
The International Controlled Transactions Schedule (ICTS) will require companies to report certain transactions with “connected” foreign companies to HMRC. Examples may include group loans, service charges and royalties.
Transfer pricing involves applying the same price to the transactions among the group as it would to third parties. HMRC will use ICTS data to verify tax risks, using digital tools and staff reviews. Don’t expect an enquiry just because there is a flag.
The last notice from HMRC will specify the types of transactions, the data fields and value limits.
Which Multinational Businesses Are Affected?
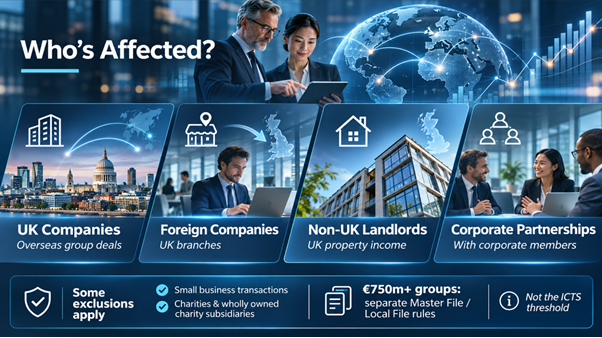
In-scope are UK companies, some overseas branches and UK branches of overseas companies.
Other companies may also be included, such as those with property income in the UK that are not UK businesses, and some corporate partnerships.
Some cross-border transactions are not reportable. There are some exclusions such as small business transactions, charities and wholly owned charity subsidiaries.
Multinational groups generating €750 million or more in revenues throughout the world are already subject to the separate Master File and Local File rules. This is not the threshold for reporting to the ICTS.
When Are ICTS Reports Due, and What If They Are Wrong?
In most situations, the ICTS deadline is after the tax return deadline to which it relates. The later of 30 September 2028 or the date specified by HMRC (up to 30 September 2027) applies to accounting periods ending on or before 30 September 2027.
If the report is not submitted or is submitted incorrectly, a fine of £300 could be imposed. The failure to do so could be worth up to £60 per day. That can be increased to £1,000 a day with permission of the tribunal if the failure continues. Some false reports may result in a fine of up to £3000.
If the tax return of a business changes, it may be necessary to amend a report. The deadline for the correction of qualifying early periods is no sooner than 30 September 2029. If you experience problems with filing your first return, HMRC will take these into account, but penalties may be applicable.
How Can Multinational Businesses Prepare for HMRC’s New ICTS Reporting Rules?
UK businesses should review their cross-border transactions such as group loans and service charges. They should check which transactions fall under the new ICTS rules and whether any exemptions apply.
Finance teams must ensure their transfer pricing records match their Corporation Tax returns. Businesses should also review intercompany agreements, pricing methods and financial records. HMRC’s final notice will confirm the exact reporting details and thresholds.
How Can LANOP Help with ICTS Compliance?
The changes will mean that certain international transactions will be compulsory to report by multinational businesses from 2027 under HMRC’s new rules (ICTS). LANOP Business & Tax Advisors guide businesses through these changes and let them know what will be required under the new rules.
Depending on your intercompany transactions, we can review your intercompany loans, management fees, royalties, and note what may be reportable. Transfer pricing techniques may also be evaluated; relevant exemptions can be reviewed and arrangements put in place to ensure that financial records reflect the Corporation Tax returns.
Contact LANOP today to prepare for the new ICTS requirements and reduce compliance risks.