From 2027, UK multinationals must file a new yearly tax report. The International Controlled Transaction Reporting Regulations 2026 (SI 2026/1156) were made on 30 October. They went before MPs on 4 November. HMRC updated its draft guidance on 11 November.
The rules start on 26 November 2026. They apply to accounting periods that begin on or after 1 January 2027. HMRC thinks about 75,000 businesses fall under the wider tax rules. It expects to raise £875 million in extra revenue by March 2031.
What Is the New ICTS Transfer Pricing Report?
The International Controlled Transactions Schedule (ICTS) gives HMRC set details about deals between linked firms in different countries. These deals can involve goods, service fees, royalties and loans.
Transfer pricing is the price one firm in a group charges another. HMRC plans to use this data to spot tax risks. It will also use it to choose which firms to check.
Which UK Multinationals Must File an ICTS?
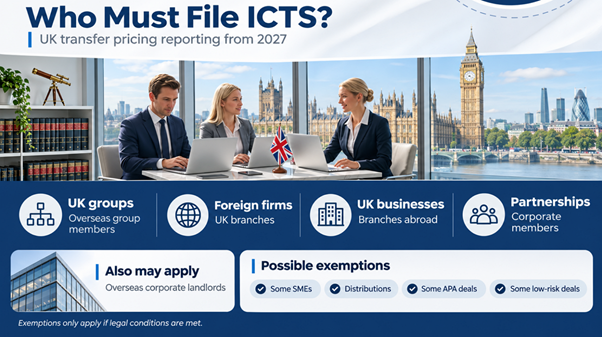
The reporting rules may affect several types of businesses with links to other countries. These include UK companies with overseas group members, foreign companies operating through UK branches and UK businesses with branches abroad.
Some overseas corporate landlords that pay UK Corporation Tax may also fall within the rules. Partnerships with corporate members could be covered as well.
Not every business or transaction will need to be reported. Certain small firms and distributions may qualify for an exemption. Some transactions covered by Advance Pricing Agreements may also be excluded. The same may apply to deals given low-risk status under an HMRC programme.
However, businesses should not assume they qualify for an exemption. They must meet the relevant legal conditions before leaving a transaction out of their report.
What Are the Key ICTS Dates for 2026 and 2027?
| Date | What changes? |
| 4 November 2026 | Final regulations laid before MPs |
| 26 November 2026 | Rules take effect; HMRC Notice planned |
| 31 December 2026 | More HMRC guidance planned |
| 1 January 2027 | First accounting periods covered |
| 30 September 2028 | Earliest filing deadline for certain short periods ending by 30 September 2027. |
Are the £1 Million and £100,000 ICTS Limits Final?
No. The £1 million and £100,000 limits appeared in earlier draft proposals. HMRC has not confirmed them as the final reporting thresholds.
Its planned Notice will explain which limits apply and which transactions businesses need to include. It will also clarify how companies should group transactions when preparing their reports.
Most ICTS reports will need to be filed with the related tax return. Businesses should wait for HMRC’s final instructions before deciding which transactions must be included.
What Happens If an ICTS Report Is Late or Wrong?
A missed report can bring a £300 penalty. If the failure goes on after a penalty notice, daily fines can reach £60. A tribunal may raise the daily amount to £1,000. Some inaccurate reports can lead to fines of up to £3,000.
You may also need to amend a report. This can happen if your tax return changes or an exemption ends. There are some exceptions. HMRC can ask for more records to check a filing. It will look at first-year cases one by one. Even so, it will not waive penalties by default.
How Can Firms Prepare for ICTS Reporting Before 2027?
Start by mapping your cross-border group deals. Include loans, services, and royalties. Next, work out which UK entities may need to file. Then match those records to your tax returns. The HMRC Notice due on 26 November will confirm the tests and fields to use.
How Can LANOP Help With ICTS Reporting?
The ICTS rules begin in 2027. UK businesses need to know which overseas deals they must report to HMRC. LANOP Business & Tax Advisors can help you review your cross-border dealings. We can also check whether the new rules apply to you.
Our team can look at intercompany loans, management fees, royalties and other group payments. We can help spot possible exemptions. We can also check that your records match the figures in your tax returns.
HMRC is still preparing its final reporting details. LANOP can help you plan and keep key information from slipping through. Contact LANOP for clear guidance on the new ICTS requirements.