Moving to Greece can lower your tax bill, but only if you apply on time. Miss the right date and your relief may start a year later than planned. The Greece tax regime deadlines changed in 2026, and many older guides still quote the 31 March rule. This guide covers Articles 5A, 5B and 5C of the Greek Income Tax Code. It shows who each regime suits, when to file, what happens if you are late, and what UK nationals should check first.
What Are the Greece Tax Regime Deadlines for 2026?
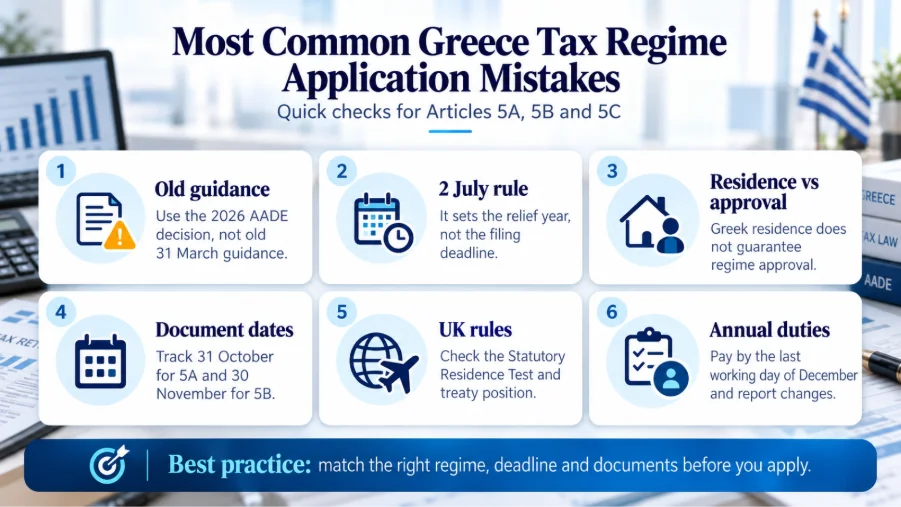
For 2026, Article 5A applications close on 30 September and Article 5B applications on 31 October. Article 5C stays open until 31 December. The 2 July cutoff decides whether you can apply in the year you arrived or have to wait for the following year.
What Changed in Greece’s Tax Deadlines in 2026?
Law 5313/2026 was published on 25 June 2026. Its Article 94 reworked Articles 5A and 5B. The old 31 March application deadline is gone. Payment of the €100,000 lump sum and the 7% tax now falls due on the last working day of December, not July.
The tax authority (AADE) then issued new decisions. Decision A.1147/2026 covers Article 5A. Decision A.1192/2026, dated 22 September 2026, covers Article 5B. Article 5C follows Decision A.1096/2026. AADE says it also covers applications submitted since 28 July 2025.
Two ideas matter most here. First, becoming a Greek tax resident and applying for a special regime are separate steps, and each has its own clock. Second, people who arrived by 2 July may apply in their arrival year or the following year. People who arrived after 2 July apply for the following year.
What Is the Greece Article 5A Application Deadline?
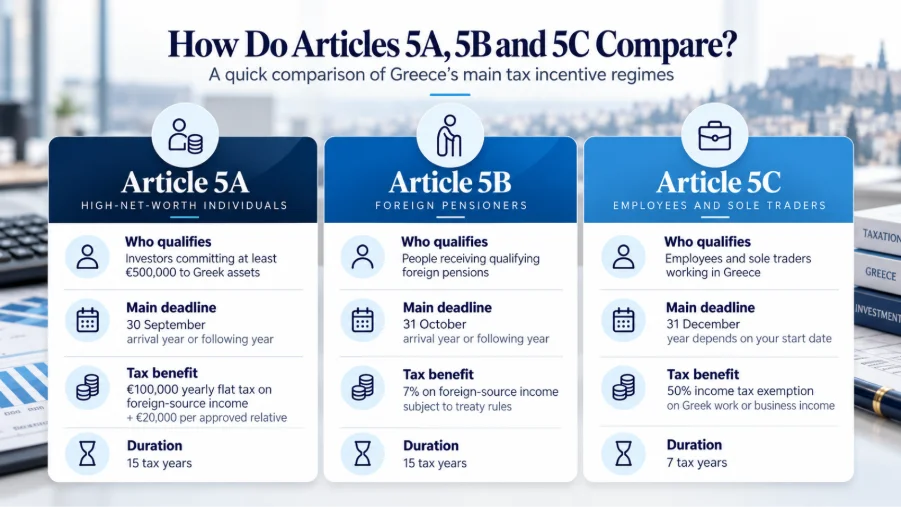
The Greece 5A application deadline is 30 September of your arrival year or the following year. Supporting papers can follow by 31 October of the year you file.
Who Meets the Greece Article 5A Requirements?
The Greece Article 5A requirements all apply together:
- You were not a Greek tax resident in seven of the previous eight years.
- You invest at least €500,000 in Greek property, businesses, securities, or shares in Greek entities. You, your spouse, a direct line relative, or a majority-owned company can invest.
- You complete the investment within three years of applying.
- Your application includes proof that the €500,000 reached an account at a Greek financial institution.
Once approved, you pay €100,000 a year, regardless of your foreign income. Each approved relative adds €20,000. Minor unmarried children living with you share your residence automatically and owe no €20,000. Income covered by the regime is not reported on your Greek tax return, though careful tax planning is still needed on the UK side.
When Should You Apply for Article 5A in 2026?
If you moved to Greece by 2 July 2026, you could apply in 2026 for 2026, or in 2027 for 2027. If you arrived after 2 July 2026, your first window is 2027. Either way, the cutoff is 30 September.
Today is 9 October 2026, so the 2026 window has closed. Your tax year of relief is the year you apply for, and approved applicants pay in one installment by the last working day of December. AADE must decide within 60 days of filing, and no later than the last working day of November.
What Is the Greece Article 5B Application Deadline?
The Greece 5B application deadline is 31 October of your arrival year or the following year. Documents can follow by 30 November. If you moved by 2 July 2026 and want 2026 treatment, you have until 31 October 2026.
Who Qualifies for Greece’s 7% Pension Tax Regime?
The Greece Article 5B requirements are shorter than Article 5A:
- You receive foreign pension income. AADE accepts payments from main or supplementary compulsory funds, occupational funds set up by law, and group pension insurance contracts.
- You were not a Greek tax resident in five of the previous six years.
- You are moving from a country that has a tax administrative cooperation agreement with Greece. AADE checks this itself, so confirm it before you move.
The 7% applies to your total foreign source income, even if it would otherwise be taxed at a lower rate or exempt. Two exceptions matter. It does not apply to income exempt in your country of residence, or income taxed differently under a tax treaty. Foreign tax you pay can be credited, but any excess is not refunded. You cannot hold Article 5A and 5B together.
When Must You Apply for Article 5B?
Apply by 31 October of your arrival year or the following year. If you moved after 2 July, you apply for the following year. You can send supporting documents until 30 November of the filing year.
AADE examines the file within 60 days and decides by the last working day of December. The 7% tax is due by that same date, in one installment. If you miss the payment, you leave the regime from that year onwards.
Can UK Pensioners Apply After the Deadline?
Sometimes. If you moved by 2 July and missed your arrival year, you can still file by 31 October of the next year. Your first year of 7% treatment then shifts to that later year. If both windows pass, you have no further route.
Do not assume every UK pension gets 7%. The 1953 treaty treats government service pensions differently from other pensions. Revoking is also final: withdraw from Article 5B, and you cannot return. Pensioners should also review how these fits with wider estate planning and inheritance tax planning before they relocate.
What Is the Greece Article 5C Application Deadline?
The Greece 5C application deadline is 31 December. Which year you apply for depends on whether you started work on or before 2 July.
Who Meets the Greece Article 5C Requirements?
According to AADE’s 5C guidance, the Greece Article 5C requirements are:
- You were not a Greek tax resident in five of the previous six years.
- You move from an EU or EEA state, or a state with a tax cooperation agreement.
- You work in Greece for a Greek legal entity or a Greek permanent establishment of a foreign company. Alternatively, you run an individual business there and have declared its start.
- You declare you will stay in Greece for at least two years.
You get a 50% income tax exemption on qualifying Greek income for seven tax years. AADE also lists an exemption from the imputed annual expense linked to your home and private cars.
How Do You Apply for Greece’s Special Tax Regimes?
The Greece tax application process has three stages: confirm eligibility, get your tax number and documents, then file and track.
Step 1: Confirm Your Tax Residency and Eligibility
Greek tax residence is judged under Article 4 of the Income Tax Code. It is separate from the special regime. Check your history too. AADE checks your prior foreign residence against its records, and first-time AFM applicants don’t need residence proof for Articles 5A and 5B. Test your eligibility before you relocate, because your investment, pension, or job decides which regime fits.
Step 2: Obtain an AFM and Prepare Your Documents
The AFM is your Greek tax identification number. You register with AADE and use myAADE and TAXISnet to file digitally. Non-residents can appoint a Greek tax representative. Foreign public documents need an apostille or consular process, plus certified translations where required, which is where our international and offshore accounting experience can help you stay organised.
Step 3: Submit Your Application and Track Approval
For Articles 5A and 5B, you can file through “My Requests” in my AADE, by registered post or courier, or in person. The date you send counts, so keep your receipt or postmark. Article 5C has its own myAADE application.
Use this checklist:
- Confirm your regime and the year you are applying for.
- Gather proof of previous residence, plus regime evidence.
- Order translations and apostilles early.
- File before the deadline, even if papers are incomplete.
- Save your submission receipt.
- Mark the document deadline and the December payment date on your calendar.
What Documents Are Required for Greece Tax Residency Applications?
Greece tax residency documents vary by regime. AADE accepts an application without them, but your file must be complete by the supplementary deadline.
Which Documents Do Articles 5A, 5B and 5C Require?
Common documents. Where AADE records do not show your foreign residence, you provide a residence certificate from your foreign tax authority. A treaty claim form with the certificate built in also works. A copy of your foreign tax return is the fallback, and confirmation from another recognized authority applies if none of these exist.
Article 5A. Proof of the €500,000 transfer to a Greek financial institution. Relatives need proof of the relationship and written consent. Evidence of completing the investment follows, within six months of completion.
Article 5B. A document from your pension provider, authority, fund or insurer showing pension payments.
Article 5C. Proof of your qualifying employment or business start, a stay declaration, and your foreign tax number with your address in Latin characters.
Can You Submit Missing Documents After the Deadline?
Yes, within limits. Article 5A allows documents until 31 October of the filing year. Article 5B allows until 30 November. Filing counts. Completing the file is a second job with its own date. Translations and certifications cause most delays, so order them before you apply. AADE’s published 5C guidance describes digital checks first and an attachment option if verification fails. It does not state a separate supplementary date.
How Long Does Greece Tax Regime Approval Take?
AADE sets official decision periods for 5A and 5B. Real Greece tax regime processing time depends on how complete your file is.
What Are the Official AADE Processing Deadlines?
For Article 5A, AADE examines the application within 60 days and decides by the last working day of November. For Article 5B, the same 60 days apply, with a latest date of the last working day of December. These are the only verified decision periods. AADE publishes no average, so treat any quoted average with caution. The published 5C guidance does not set out a comparable period.
What Happens If You Miss a Greece Tax Regime Deadline?
You may have a later window. The answer depends on the regime and how many windows remain.
| Situation | Possible consequence | Next action |
| Missed 5A date in arrival year (moved by 2 July) | You may file by 30 September next year for that later year | Prepare your investment evidence now |
| Missed both 5A windows | The decision shows no later route | Seek advice before assuming you are excluded |
| Missed 5B date in arrival year | You may file by 31 October next year | Gather pension and residence proof |
| Filed 5C in the following year (started by 2 July) | AADE assesses the following year, not the start year | Review the tax you paid in the start year |
| Missed supplementary document date | An incomplete file is not approved automatically | Send documents and contact the office |
| Approval arrived after the intended year | Relief still ties to the year you applied for | Check the December payment date |
What Should UK Nationals Check Before Moving to Greece?
The Greece tax regime for UK nationals works alongside UK tax law. It does not replace it.
Will You Still Pay UK Tax After Becoming a Greek Tax Resident?
It depends on your UK residence status under HMRC’s Statutory Residence Test. The automatic overseas tests look at days spent in the UK, including fewer than 16 days if you were UK resident in one of the previous three years. The automatic UK tests include 183 days. A sufficient ties test applies in between. Split-year treatment may cover the year you leave, but only in set cases.
Dual residence is possible. The 1953 UK and Greece Double Taxation Convention gives credit relief for tax paid in each country. UK-source income, such as rent from UK property, can remain taxable in the UK and will usually still need reporting through Self Assessment. UK landlords may also want support from our landlord accounting team. Under Article 5A, you cannot set off tax paid abroad against the €100,000.
How Are UK Pensions and Remote Work Income Treated?
The 1953 treaty separates pension types. Article VIII exempts pensions from government service in the other country. Article X exempts other pensions from UK tax for a Greek resident who is taxed on them in Greece. The treaty is old, so confirm how both tax authorities apply it to your pension. That check also matters for Article 5B’s treaty exception.
Cross-border employment and foreign clients need a separate review, covering payroll and social security. Your facts decide the outcome.
Does Article 5C Reduce Your Total Tax Bill by 50%?
No. The 50% exemption applies to income tax on qualifying income. It does not halve your whole bill. Social security contributions to EFKA stay separate. Sole traders may also have VAT and business duties. Your savings depend on your income, deductions and structure.
Conclusion: Which Greece Tax Regime and Application Timeline Is Right for You?
There is no single best route. The right one depends on your income, where you lived before, when you move and what you plan to do in Greece.
If you are an investor, start with Article 5A. Look at the €500,000 investment, the proof of transfer, and the December payment. If you are a pensioner, confirm that your type of pension and the treaty position support Article 5B. Employees should compare their start date with 2 July, because that tells you which year your relief begins. Freelancers and remote workers need to check how their work is set up and where their income comes from before counting on Article 5C. If you have already missed a deadline, don’t write yourself off. A later window may still be open. And if you live in the UK, look at your UK tax position at the same time as the Greek application.
Whatever your situation, confirm your eligibility first. Filing too early, or on the wrong basis, can cost you a year of relief.
Not sure which Greek tax regime fits you, or when to apply? Lanop can help you review your UK tax position, understand the key deadlines and plan your next steps. Contact Lanop today to book a free consultation with our team before you make the move.
Frequently Asked Questions
Not for 2026, since the 30 September deadline has already passed. If you arrived in 2026, you can apply until 30 September 2027 for 2027
No. Law 5313/2026 removed the 31 March deadline. AADE Decision A.1192/2026 now sets the deadline for 31 October of your arrival year or the following year, with supporting documents due by 30 November.
Yes, because you apply after starting. If you started on or before 2 July, apply by 31 December for that year or later for the next. If you started after 2 July, apply by 31 December of the following year.
Sometimes. AADE allows 5C alongside 5A or 5B if the conditions for each are met when the application is accepted. Articles 5A and 5B can’t be used together. Ask an adviser which mix applies to you.
Each spouse needs their own application and their own qualifying job or business. AADE’s 5C guidance describes individual applications and no family extension, unlike Article 5A.