A director’s loan account records money moving between you and your company. Amounts properly treated as salary, dividends, or reimbursed business expenses are not themselves loans, although they may be credited through the loan account and affect its balance. An overdrawn balance means you personally owe money back to your company.
This balance can create company tax and personal tax problems. If qualifying loans remain unpaid after the deadline, Section 455 tax may apply.
For loans made from 6 April 2026, Section 455 is 35.75%. Many directors worry about these tax bills and complicated repayment rules. At Lanop, our Chartered Accountants have guided UK directors for nearly two decades. This guide explains each step clearly, helping you act confidently.
Director’s Loan Account Rules briefly
- Section 455 tax may be 35.75% for qualifying loans made from 6 April 2026.
- Qualifying loans made from 6 April 2022 to 5 April 2026 use 33.75%.
- The normal Section 455 tax deadline is 9 months and one day after year-end.
- Loans above £10,000 can also create a personal tax charge for you.
- HMRC’s official interest rate is 3.75% from 6 April 2026. HMRC can update official rates, so the applicable rate should be checked for the relevant period.
What Is a Director’s Loan Account?
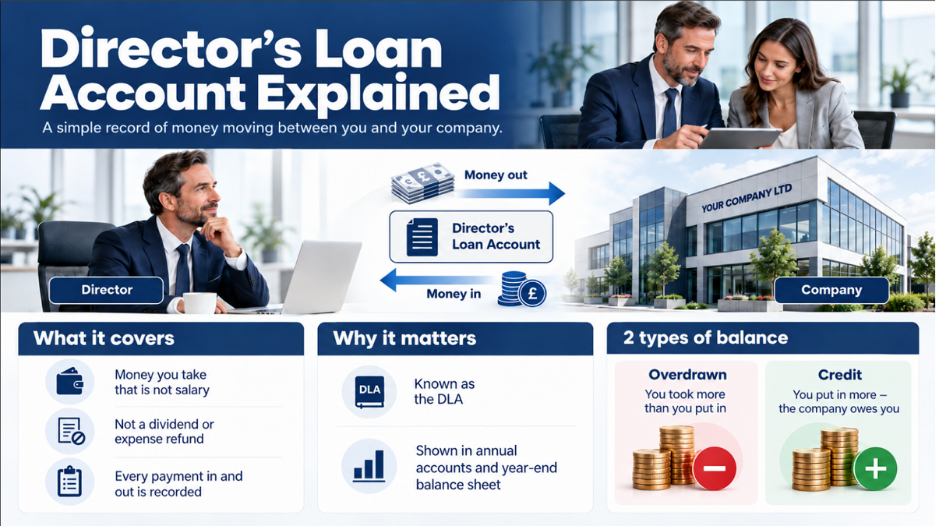
A director’s loan account records money moving between you and your company. It covers money you take that is not properly treated as salary, dividend, or an expense repayment. It also records money you pay into or lend to the company. The company must keep a record of relevant payments in and out. That record is known as the director’s loan account or DLA. Directors’ loan account accounting means you show the balance in your annual accounts. It sits on the balance sheet at the end of each year.
There are 2 types of balances:
- Overdrawn means you have taken more from the company than you put in.
- Credit means you put in more, and the company owes you.
How Does It Work?
The company records every payment entering or leaving this account. This record helps your accountant prepare accurate company accounts each year.
It also shows whether the account balance is overdrawn or credited. An overdrawn balance means you owe money to your company. A credit balance means your company owes money back to you.
What are the Director Loan Account Rules for 2026?
The director’s loan account rules depend on who owes money to whom. A credit balance is simple because the company can just repay you. An overdrawn balance is where the tax problems start for most directors.
The overdrawn directors’ loan account rules changed one key number in 2026. The tax rate on new loans rose from 33.75% to 35.75% this year. Here are the directors’ loan account rules for 2026 in one simple table:
| Date the loan was made | Section 455 rate | Tax on a £20,000 loan |
| 6 April 2026 onwards | 35.75% | £7,150 |
| 6 April 2022 to 5 April 2026 | 33.75% | £6,750 |
| 6 April 2016 to 5 April 2022 | 32.5% | £6,500 |
Rates reflect HMRC updates after the Autumn Budget 2025 dividend tax rise.
What Happens If a Director’s Loan Account Is Overdrawn?
A close company may need form CT600A for qualifying loans to participators, such as shareholder-directors. If the loan remains outstanding after the relevant deadline, a Section 455 tax charge may apply.
Section 455 is a tax charge, not a fine. Relief may later be available if the loan is repaid, released, or written off. HMRC can charge interest on unpaid Section 455 tax, and that interest cannot be reclaimed.
How Much Tax Do You Pay on an Overdrawn Loan?
Section 455 tax is calculated using the applicable rate and chargeable balance:
| Loan left unpaid | Tax at 35.75% |
| £5,000 | £1,787.50 |
| £10,000 | £3,575 |
| £20,000 | £7,150 |
| £50,000 | £17,875 |
You can work out your own bill with quite an easy sum. Multiply the qualifying unpaid balance by 0.3575 for an estimate. This applies only to loans made on or after 6 April 2026. Older loans use 33.75%, so keep each loan dated in your records.
When Does Section 455 Tax Apply and What Is the Deadline?
Section 455 can apply where a close company makes a loan or advance to a participator, such as a shareholder-director, or in certain circumstances an associate of a participator. The loan must still be outstanding after the relevant deadline for the tax charge to arise. The normal deadline is nine months and one day after the end of the accounting period in which the loan was made.
A 31 March 2027 year-end means repaying by 31 December 2027. The Section 455 tax is normally due on 1 January 2028. Say you borrowed 40,000 in May 2026 and miss that date. Your company would then owe £14,300 in tax under Section 455 rules.
How Does a Director’s Loan Account Affect Corporation Tax?
A Section 455 tax charge is paid by the company alongside its Corporation Tax liabilities. The charge is not a deductible business expense, so it does not reduce taxable profits. Paying the charge does not clear the loan or remove the director’s obligation to repay it.
Where Section 455 tax has already been paid, the company may claim relief when the loan is repaid, released, or written off. However, HMRC will generally not repay the tax until nine months and one day after the end of the accounting period in which that event occurred. A claim must normally be made within 4 years of the end of the relevant financial year. Depending on timing and circumstances, the claim may be made through form CT600A or form L2P.
Who Pays Tax on a Director’s Loan: You or the Company?
Director’s loan account tax rules can create different charges for the company and the director. Section 455 is a company-level charge, while a separate personal tax charge can arise under the beneficial-loan rules. Use this table to see the main potential tax consequences.
| What happens to the loan | Company pays | You pay |
| Repaid within nine months and one day | No Section 455 tax if qualifying repayment is effective | Beneficial-loan tax may still apply for the period before repayment |
| Not repaid within nine months and one day | 35.75% Section 455 tax may apply to qualifying 2026 loans | Beneficial-loan Income Tax may also apply where relevant |
| Over £10,000 with low or no interest | Class 1A NI may apply to the taxable benefit | Income Tax may apply to the taxable benefit |
| Written off or released | National Insurance obligations may arise | Income Tax may apply to the amount released |
Do You Pay Personal Tax on a Director’s Loan?
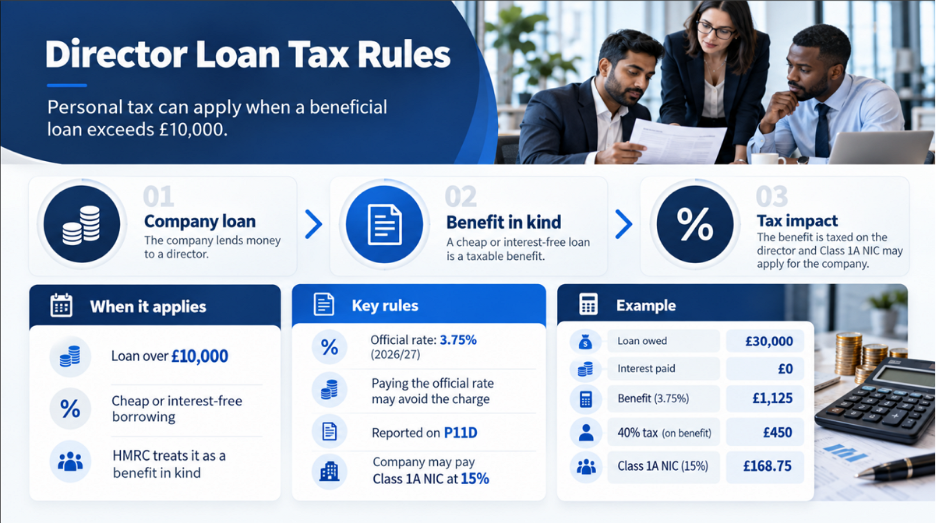
A taxable beneficial-loan charge may arise where qualifying employment-related loans exceed the £10,000 exemption and the director pays less than HMRC’s applicable official rate of interest. HMRC treats cheap or interest-free borrowing as a benefit in kind where the relevant conditions are met.
HMRC’s official rate is 3.75% from 6 April 2026. Paying at least the applicable official rate may prevent a taxable beneficial-loan charge. If you pay less, you may pay Income Tax on the taxable benefit. The benefit must also be reported to HMRC under the applicable benefits reporting rules, which may include P11D reporting. The company may pay Class 1A National Insurance at 15% on the taxable benefit.
Here is a simple example:
- Say you owe £30,000 for the full year and pay no interest.
- That gives a yearly benefit of £1,125 because 3.75% of £30,000 is £1,125.
- A higher-rate taxpayer would pay 40% of that, which is £450.
- The company also pays £168.75 in Class 1A National Insurance on top.
Can You Repay a Director’s Loan Before the Section 455 Deadline?
Yes, genuine repayment before the relevant deadline can prevent a Section 455 charge in practice, subject to the anti-avoidance rules. Do not simply relabel a withdrawal after the transaction has happened. The director’s loan account repayment should be supported by clear records throughout.
How Can You Repay the Loan?
The directors’ loan account repayment method depends on the circumstances. You should choose a genuine method with correct tax treatment. Never change labels simply to avoid an expected tax charge. Below is a complete roadmap explaining how to repay your director’s loan:
Direct Personal Repayment
You can transfer personal money into your company bank account. This directly reduces the balance owed by the director. Keep the bank confirmation and accounting entry for future evidence.
Lawful Dividend Credit
A valid dividend may reduce the outstanding loan balance. However, the company needs enough distributable profits for payment. Correct approval documents must support the dividend decision clearly.
Salary Or Bonus
A salary or bonus may reduce the loan balance. Payroll must process related income tax and National Insurance amounts. This method may affect both company costs and personal tax.
Expense Reimbursement
Genuine business costs paid personally may be credited to your account. Each expense needs a business reason and supporting receipt. Private spending cannot become business expenses through simple relabelling.
Loan Writeoff
A company may sometimes release or write off balances. This does not create a simple tax-free solution. The director may face Income Tax on the amount released or written off, and the company may also have National Insurance reporting and payment obligations depending on the circumstances.
Professional advice should come before any loan release decision. Writing off balances can create unexpected tax and reporting issues. It can also create serious concerns during company insolvency proceedings.
What Is the 30 Day Rule for Directors’ Loans?
The director’s loan account 30-day rule is designed to restrict Section 455 relief where a repayment is followed by further borrowing. It is a matching rule rather than a blanket ban on every repayment and re-borrowing. A separate arrangements rule can also apply to larger balances even outside the 30-day period.
- The 30-day matching rule can apply where repayments total £5,000 or more and new qualifying loans of £5,000 or more are made within the relevant 30-day period.
- A separate arrangements rule can apply where at least £15,000 is outstanding immediately before a repayment and arrangements exist for at least £5,000 of new qualifying borrowing.
Where these anti-avoidance rules apply, some or all of the repayment may not produce the expected Section 455 relief. Relief can still become available when the relevant loan is genuinely and permanently repaid, subject to the detailed rules.
What Are the Risks and Penalties of an Overdrawn Loan?
An overdrawn loan can hurt both your company and you in several ways:
- The main risks of a director’s loan account are cash loss and extra tax.
- Section 455 tax can lock up cash that the company needs.
- A director’s loan account penalty can follow if you file or pay late.
- Wrong figures on form CT600A can also lead to an HMRC enquiry.
- If the company fails, a liquidator can demand that you repay the loan.
- Lenders and buyers may also see a large loan as a red flag.
What Mistakes Do Directors Often Make with Loan Accounts?
Our team often sees the same few errors repeatedly each year:
- Taking cash from the company without recording it as a loan entry.
- Forgetting the nine-month-and-one-day deadline and then triggering a Section 455 tax charge.
- Using the old rate of 33.75% on loans made after April 2026.
- Ignoring the £10,000 beneficial-loan exemption and then missing the required benefit reporting.
- Repaying on 30 December and then borrowing the same sum on 5 January.
How Can You Avoid Penalties on a Director’s Loan Account?
The directors’ loan account penalty often follows poor recordkeeping. Some penalties relate directly to tax, while others involve reporting. Early action usually costs less than correcting mistakes after deadlines. These simple habits keep you safe and keep your tax bill low:
- Check your loan balance every month using cloud software such as Xero.
- Repay the full balance before the nine-month-and-one-day deadline where possible.
- Charge and pay the applicable official rate to reduce benefit-in-kind risk.
- Keep a written loan agreement and bank proof for every single payment.
- Check the 30-day matching and arrangements rules before repaying and then borrowing again.
- Ask a chartered accountant to review your balance before each year-end.
How Can LANOP Help With Director’s Loan Account Problems In Practice?
Director loan issues often involve accounting, tax, cash flow, and timing for businesses. Lanop Business and Tax Advisors is a UK firm of chartered accountants. We have guided UK entrepreneurs and families through tax for nearly two decades.
Every client gets a dedicated chartered accountant who answers within the same day. Our team handles limited company tax, bookkeeping, and payroll every day. We use Xero and QuickBooks so director loan balances stay clear all year. This guide follows HMRC and GOV.UK guidance as of October 2026.
Official Sources
GOV.UK: Director’s loans – overview and tax rules when you owe your company money.
HMRC Company Taxation Manual: CTM61505 (Section 455 rates), CTM61630 (30-day rule), and CTM61635 (arrangements rule).
HMRC: Beneficial loan arrangements – official rates of interest.
GOV.UK: Reclaim tax paid by close companies on loans to participators (L2P).
Frequently Asked Questions
A close company may need CT600A for a qualifying overdrawn loan to a participator. A Section 455 tax charge may apply at 35.75% to qualifying loans made from 6 April 2026 that remain outstanding after the relevant deadline.
For qualifying loans made from 6 April 2026, the company may pay Section 455 tax at 35.75% of the chargeable outstanding balance. A £10,000 chargeable balance would produce a £3,575 Section 455 tax charge.
Section 455 generally applies where a close company makes a loan or advances to a participator, such as a shareholder-director, and the amount remains outstanding for nine months and one day after the end of the relevant accounting period.
Repay on time and file form CT600A correctly where required. If the beneficial-loan rules apply, charge and pay at least the applicable HMRC official rate where appropriate, and ask a chartered accountant to review the position.
The normal deadline is nine months and one day after your accounting period ends. For a 31 March year-end, this usually means repayment by 31 December, with any Section 455 tax normally becoming due on 1 January.
Final Thoughts
Most director loan problems begin with unclear records or late planning. You can reduce these risks by reviewing balances throughout the year. However, every company is different, and one small error can cost thousands. That is where LANOP can help you stay calm and compliant.
Our Chartered Accountants can review your balance and plan suitable repayment options. If your account is overdrawn, do not wait until deadlines approach. Speak with LANOP early so you can plan your next steps confidently.